When Your Mortgage Is Bigger Than Your Retirement Savings
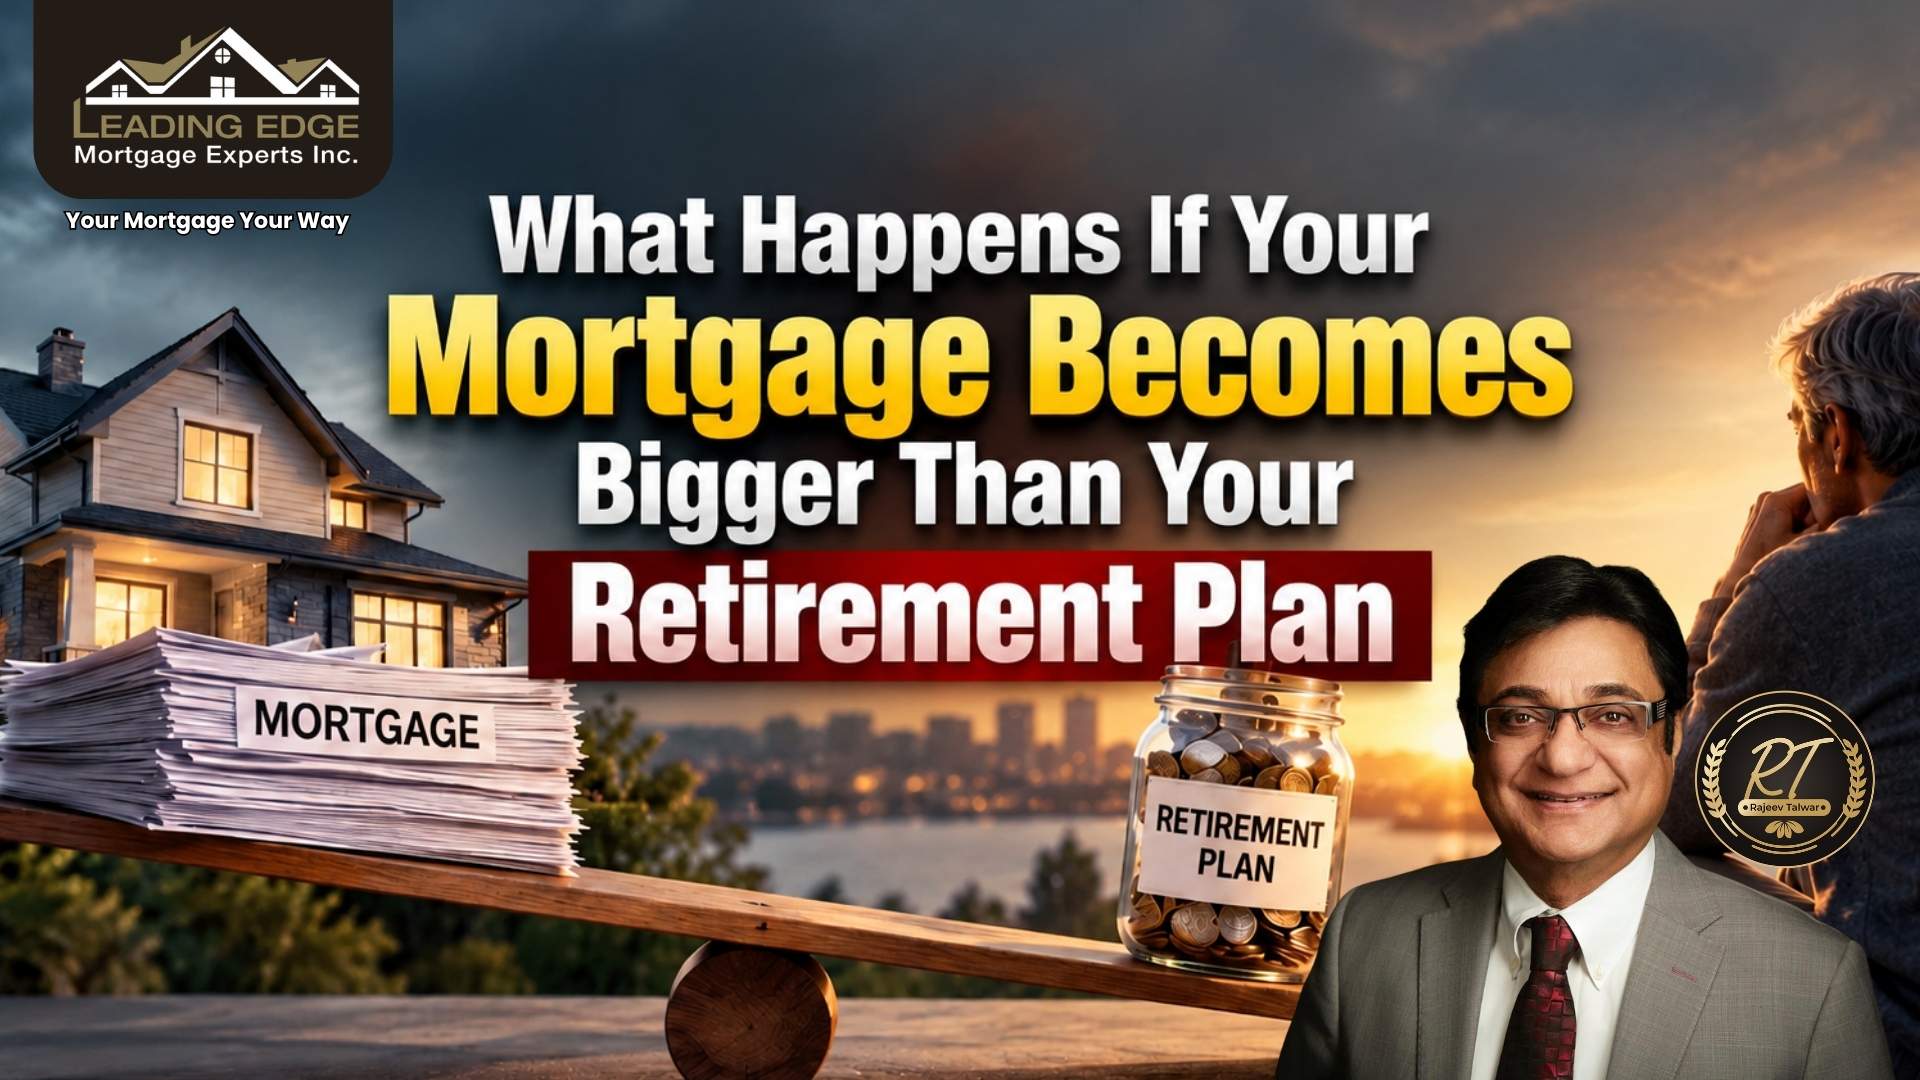
When Your Mortgage Is Bigger Than Your Retirement Savings
For many Canadians, buying a home is one of the biggest financial decisions they will make. A mortgage can help turn homeownership into a reality, but it can also become a significant long-term financial obligation.
As home prices and mortgage balances increase, some homeowners may eventually find themselves in a situation where their mortgage is larger than their retirement savings. This does not automatically mean they are financially unprepared for retirement, but it is a situation that deserves careful consideration.
The important question is not simply how much you owe on your home. It is whether your mortgage, retirement savings, income, and home equity work together to support your long-term financial goals.
At Leading Edge Mortgage Experts Inc., we believe mortgage planning should look beyond today’s affordability and consider your financial future as well.
Understanding Your Mortgage and Retirement Savings
Your mortgage and retirement savings play very different roles in your financial plan.
A mortgage is a liability that requires regular payments, while retirement savings are assets intended to provide financial support when employment income decreases or stops.
If your mortgage balance is significantly higher than your retirement savings, a large portion of your financial position may be tied to your home. This is not necessarily a concern if you have substantial home equity, pension income, investments, or other assets.
However, it is important to understand that home equity and retirement savings are not the same thing. Accessing home equity may require selling your home, refinancing, downsizing, or using another borrowing strategy.
Why a Large Mortgage Can Affect Retirement
A large mortgage can affect retirement planning because mortgage payments consume part of your monthly income.
When a significant portion of your income goes toward housing costs, you may have less money available for RRSP contributions, TFSA savings, investments, emergency funds, or other financial goals.
For example, a homeowner may focus heavily on paying down their mortgage while postponing retirement contributions. Although reducing debt can be beneficial, delaying investments for too long can reduce the amount of time available for potential compound growth.
The goal is therefore not necessarily to eliminate your mortgage as quickly as possible. Instead, it is important to find a balance between managing debt and building retirement assets.
Your Home Is Valuable, But It May Not Provide Retirement Income
Homeownership can create significant wealth through mortgage payments and potential property appreciation. However, the value of your home does not automatically provide cash for retirement expenses.
For example, you may own a home worth $1 million while still having a substantial mortgage balance. The difference between the home’s value and the amount you owe represents your equity.
That equity is an important part of your net worth, but you may not want to sell your home simply to access it during retirement.
This is why retirement planning should consider both home equity and liquid financial assets.
What Happens If You Retire With a Mortgage?
Carrying a mortgage into retirement is possible, but it requires careful planning.
During your working years, mortgage payments may be supported by employment income. After retirement, your income may come from pensions, government benefits, RRSPs, TFSAs, investments, or other sources.
If a significant portion of that income must continue going toward your mortgage, you may have less money available for everyday expenses, travel, healthcare, home maintenance, or unexpected costs.
The key question is whether your expected retirement income can comfortably support your mortgage payment and other expenses.
Interest Rates Can Change Your Financial Picture
Interest rates are another important consideration.
When your mortgage comes up for renewal, the available interest rate may be different from your previous rate. A higher rate could increase your borrowing costs and affect your monthly cash flow.
This can be particularly important for homeowners approaching retirement because there may be less time to adjust their financial strategy.
Reviewing your mortgage well before renewal can help you understand how different scenarios could affect your future budget.
The Opportunity Cost of Paying Down Your Mortgage
Paying down your mortgage reduces your outstanding debt and can lower the amount of interest you pay over time. However, putting every available dollar toward your mortgage may also mean contributing less toward retirement investments.
Money directed toward mortgage prepayments cannot simultaneously be invested elsewhere.
For some Canadians, increasing retirement contributions may be an important priority. For others, reducing mortgage debt may provide greater financial comfort.
The appropriate balance depends on your income, mortgage rate, investment strategy, retirement timeline, and overall financial goals.
What If Your Mortgage Is Bigger Than Your Retirement Savings?
If your mortgage balance is currently larger than your retirement savings, the first step is to review your complete financial picture.
Consider:
- Your outstanding mortgage balance
- Your home’s estimated value
- Your current mortgage interest rate
- Your monthly mortgage payment
- Your RRSP and TFSA balances
- Pension benefits you may receive
- Other investments and savings
- Your expected retirement age
- Your estimated retirement expenses
Looking at these factors together provides a much clearer picture of your financial position than comparing two numbers alone.
You may have significant home equity that offsets part of the mortgage, or you may discover that increasing retirement contributions should become a greater priority.
Could Downsizing Be an Option?
For some homeowners, downsizing can become part of their retirement strategy.
Selling a larger property and purchasing a smaller home may potentially reduce mortgage debt, property taxes, maintenance costs, utilities, and other housing expenses. Depending on the circumstances, downsizing may also release some home equity.
However, selling costs, the price of the replacement property, moving expenses, and personal preferences should all be considered before making such a decision.
Downsizing is simply one potential strategy among several.
Planning Ahead Can Make a Difference
The earlier you review your mortgage and retirement strategy, the more flexibility you may have.
If retirement is still several years away, you may have time to gradually reduce your mortgage balance while increasing retirement contributions.
Regularly reviewing your mortgage, savings, investments, income, and future housing plans can help identify potential challenges before they become more difficult to manage.
Small adjustments made over time can have a meaningful impact on your financial position.
Questions to Ask Before Retirement
If your mortgage is currently larger than your retirement savings, consider asking yourself:
- How much will I owe when I retire?
- Can my expected retirement income cover my mortgage payment?
- How much home equity do I have?
- Am I contributing enough toward retirement?
- What happens if mortgage rates are higher at renewal?
- Would downsizing eventually make sense for my circumstances?
- Do I have enough liquid savings for unexpected expenses?
These questions can help you evaluate whether your current strategy supports your long-term goals.
A Mortgage Should Support Your Financial Future
A mortgage should be viewed as part of your broader financial plan rather than as a separate financial decision.
At Leading Edge Mortgage Experts Inc., we help Canadians understand their mortgage options while considering their long-term financial priorities. Whether you are purchasing a home, renewing your mortgage, refinancing, or accessing home equity, understanding how your mortgage fits into your overall financial strategy can help you make more informed decisions.
If your mortgage has grown larger than your retirement savings, now may be a good time to review your financial position and explore your options.
Contact Us Today
Rajeev Talwar
Principal Mortgage Broker / Owner
Leading Edge Mortgage Experts Inc.
Licence Number: M08002849
Telephone: 905-819-1001
Email: rajeevtalwar@thehomemortgage.ca
Rajeev Talwar
Lic #M08002849
Mississauga, Mortgage Broker/Owner
Tel: 905-819-1001
Fax: 905-819-1002
Email: rajeevtalwar@thehomemortgage.ca